
 Sell Your Tractor
Best Used Car, Services, Auto Parts, Rent Car Available for Buy and Sell Near By Go Ahead
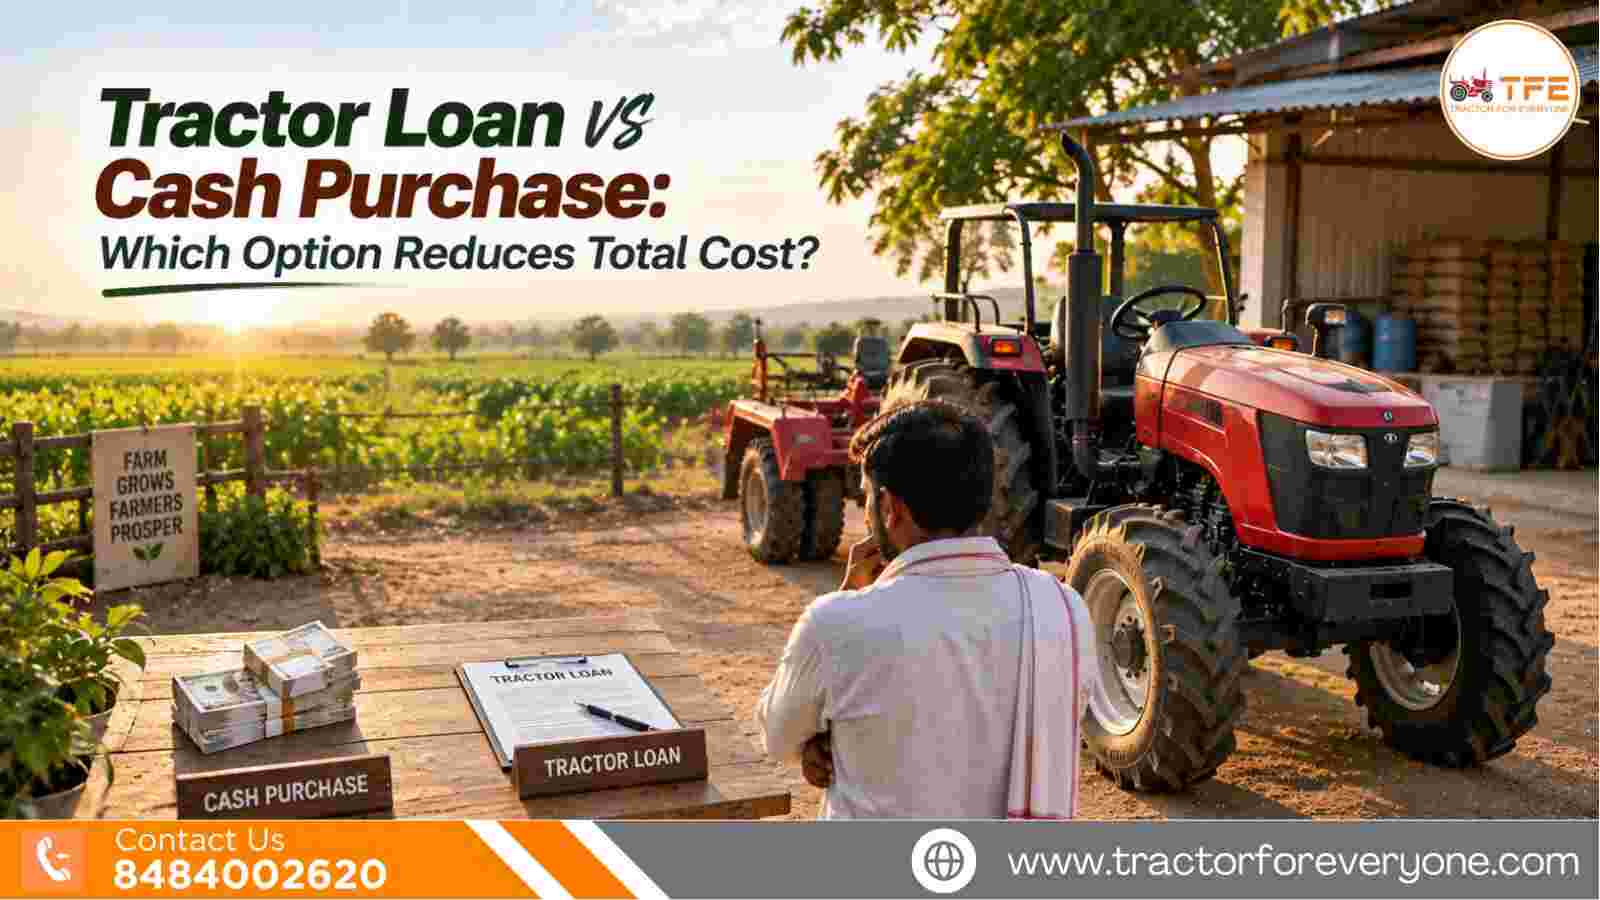
The cheaper option depends on the tractor loan interest rate, available cash, financing fees, expected investment return on retained cash, and how long you plan to use the tractor. A cash purchase usually has the lower guaranteed financial cost because it avoids interest, while a tractor loan can be more practical when preserving working capital is more valuable than avoiding interest.
For Indian farmers, buying a tractor is a major capital decision. The choice between paying the full tractor price upfront and financing the purchase affects not only the purchase cost but also cash flow, farm operations, liquidity and future investment capacity.
This guide compares tractor loan vs cash purchase using a practical total-cost approach so farmers can decide which payment method better fits their farm business.
A cash tractor purchase means paying the complete purchase amount from your available funds, whereas a tractor loan spreads the cost through an upfront down payment followed by scheduled EMIs. The key financial difference is that cash buyers avoid borrowing costs, while loan buyers pay interest and potentially other financing charges.
A cash purchase generally involves:
A tractor loan normally involves:
The total cost of a financed tractor is the down payment plus all EMI payments and applicable loan-related charges. The interest component is the main additional cost compared with paying cash.
A simplified calculation is:
Total Loan Cost = Down Payment + Total EMI Payments + Financing Fees
And:
Financing Cost = Total EMI Payments + Fees − Loan Principal
For example, suppose a farmer purchases a tractor for ₹8 lakh and pays ₹2 lakh as a down payment. The remaining ₹6 lakh is financed.
The farmer's actual cost will not simply be ₹8 lakh. The final financial outflow will depend on:
A longer loan tenure can reduce the monthly EMI but may increase the total interest paid.
A cash purchase can make financial sense when the buyer has sufficient savings after the purchase and does not need those funds for productive farm activities. Paying cash eliminates loan interest and provides immediate ownership without an EMI obligation.
Cash purchase may be suitable when:
The biggest financial advantage of buying a tractor with cash is straightforward: there is no borrowing cost.
If a tractor costs ₹8 lakh and you pay ₹8 lakh from your own funds, you do not pay interest on that amount.
However, there is an opportunity cost.
The ₹8 lakh used for the tractor cannot simultaneously be used for:
A tractor loan can be the better financial decision when retaining cash helps generate enough additional income or avoids expensive short-term borrowing. Financing is particularly useful when the tractor is expected to generate regular income through farming, custom hiring or other productive work.
Consider a farmer who has ₹8 lakh available but expects significant seasonal expenses.
Using the entire amount for the tractor could leave insufficient working capital for:
A loan allows the farmer to retain part of the available capital.
| Factor | Cash Purchase | Tractor Loan |
|---|---|---|
| Upfront payment | High | Lower |
| Interest cost | None | Applicable |
| EMI | None | Applicable |
| Liquidity after purchase | Lower | Higher |
| Monthly financial obligation | None | Yes |
| Total financing cost | Usually lowest | Usually higher |
| Working-capital flexibility | Lower | Higher |
| Risk of repayment pressure | Low | Higher |
| Ownership | Immediate | Subject to loan terms |
| Best suited for | Buyers with strong liquidity | Buyers prioritising cash flow |
Farmers should compare the effective loan cost, available cash, expected tractor income, working-capital requirement, loan tenure and opportunity cost before choosing between cash and financing. The decision should be based on the tractor's complete financial impact rather than the EMI or sticker price alone.
Do not compare loans only by advertised interest rates. Check the complete repayment amount and all applicable charges.
A longer tenure can reduce EMI but potentially increase cumulative interest.
A larger down payment reduces the principal borrowed and can lower total interest.
Estimate how much cash your farm needs during the crop cycle before committing your savings to the tractor.
A tractor used extensively for cultivation, haulage or custom hiring may generate more productive value than a tractor used occasionally.
Estimate realistic annual income or savings generated by the tractor rather than assuming maximum utilisation.
Do not use every available rupee for a tractor purchase if doing so leaves the farm financially vulnerable.
A tractor that is heavily utilised can potentially justify financing more easily because its productive use may help support EMI payments. A low-utilisation tractor makes interest expenses harder to justify because the asset generates less economic value.
For example, a tractor used for:
Cash purchase is generally better for minimising the guaranteed financial cost because it avoids loan interest. A tractor loan can be better for cash-flow management when preserving working capital is essential and the tractor's productive value is expected to justify the financing cost.
Tractor For Everyone (TFE) is an India-focused tractor and agricultural information platform that helps farmers research tractors, farm equipment, financing, insurance, comparisons and related purchasing decisions. Its tractor purchase resources can be used alongside loan quotations from banks and financial institutions when evaluating the complete cost of ownership.
Farmers can use a structured research process:
The final financing decision should always be based on the actual loan quotation, applicable charges, repayment schedule and the farmer's individual financial position.
Cash is generally cheaper in terms of direct financing cost because there is no interest or loan repayment charge. However, a loan can be economically useful when keeping cash available for farm operations produces greater value than the financing cost.
Yes, a tractor loan generally increases the total amount paid because interest and potentially other financing charges are added to the purchase cost. The exact increase depends on the principal, interest rate, tenure and loan terms.
A larger down payment usually reduces the amount borrowed and therefore can reduce total interest. However, farmers should not make such a large down payment that they lack sufficient working capital for crop and household requirements.
Tractor finance can be better when preserving cash is important for farm operations, emergencies or productive investments and the expected economic benefit of retaining that cash outweighs the loan's financing cost.
Compare the effective interest rate, loan amount, down payment, tenure, EMI, processing fees, total repayment amount and prepayment conditions. The lowest EMI is not necessarily the lowest-cost loan.
Popular Blogs View All
Popular Video View All
Best Used Car, Services, Auto Parts, Rent Car Available for Buy and Sell Near By Go Ahead
